Wall Street Quietly Takes Over DeFi: The 90 Percent Handover
The Death of the Public Pool: How Institutional PropAMMs Rewired Decentralized Trading
Wall Street did not conquer decentralized finance by banning it; they absorbed its order flow.
Every time a user initiates a token swap on a major aggregator interface, the assumption remains that public smart contracts and community-funded liquidity pools are settling the trade. The underlying reality has shifted entirely: modern decentralized exchanges function less like autonomous market booths and more like high-frequency order routers.
Recent market analytics reveal a massive architectural realignment within decentralized trading venues. Private liquidity providers and proprietary automated market makers (propAMMs) now account for between 15% and 27% of total daily on-chain spot DEX volume globally. More critically, in targeted high-throughput environments—such as SOL-to-stablecoin pairs routed through leading platforms like Jupiter—proprietary market-making operations capture over 90% of total volume. The open, user-funded liquidity pool is no longer the dominant execution venue for mature digital assets.
🏛️ The Re-Emergence of the Electronic Specialist
The structural transformation of on-chain trading is best understood through the lens of transaction costs and market efficiency. The foundational model of decentralized finance relied on constant-product automated market makers (CPMMs), where passive capital providers deposited token pairs into public smart contracts. While this system solved early cold-start liquidity challenges, it exposed passive liquidity providers to severe structural losses, known technically as loss-versus-rebalancing (LVR).
In volatile environments, external arbitrageurs systematically exploit static AMM quotes before public pools can reprice. The adoption of high-performance blockchains featuring sub-second slot times—such as networks achieving 300-millisecond block intervals—radically altered these mechanics. High-speed block production reduces stale-price exposure, allowing institutional trading desks to deploy private inventory directly on-chain via algorithmic propAMMs without subjecting their capital to predatory public arbitrage.
"Public smart contracts have transitioned from open liquidity pools into settlement rails for private market makers."
Comprehensive transaction studies across major trading venues demonstrate the commercial driver behind this shift. Statistical evaluations of over 20 million propAMM fills demonstrate that median execution costs fell within 0.72 basis points of centralized exchange midpoints. Furthermore, 91.9% of evaluated propAMM fills outperformed the lowest institutional fee tiers available on major centralized exchanges. Front-end aggregators automatically route trades to these proprietary desks because they deliver vastly superior execution for end-users, effectively privatizing price formation.
⚙️ The Dark Pool Mechanism: Wall Street’s 1990s Playbook in DeFi
To understand where crypto market structure is heading, one must look to traditional equity markets in 1998, when the SEC introduced Regulation ATS (Alternative Trading Systems). That regulatory shift allowed private electronic communications networks (ECNs) and institutional dark pools to internalize retail order flow away from public exchange floors like the NYSE. Wall Street realized that matching buy and sell orders internally using private inventory was far more profitable than sending them to a public order book where competitors could front-run the trade.
Today’s propAMM and RFQ architecture on permissionless blockchains is a direct structural mirror of the late-1990s dark pool expansion. Just as institutional brokers established off-exchange internalized execution venues, top-tier crypto desks now run permissioned, closed-source pricing engines that communicate with front-end routers via off-chain API calls, settling only the final state on-chain.
What the market is witnessing is not a temporary anomaly, but an economic sorting mechanism. Institutional desks absorb highly liquid, mature digital assets where reference prices exist across multi-venue arbitrage networks, leaving traditional public AMMs to service the long-tail illiquid token market. The uncomfortable reading of this evolution is that peer-to-peer liquidity was never an optimal market design for mature assets—it was merely a temporary bootstrap mechanism while institutional infrastructure caught up.
| Competing Force | The Irreconcilable Friction |
|---|---|
| 🏢 Public AMMs (Passive LPs) vs Institutional PropAMMs | 🏢 Sacrificing transparent pool reserves for superior institutional price execution. |
| Aggregator Routers vs Open Protocol Governance | 💰 Centralizing market access through permissioned, off-chain liquidity provider selection. |
| Tokenized Equity Issuers vs Permissionless Pools | 💰 Routing traditional stock assets exclusively through identity-verified institutional market makers. |
📊 Real-World Asset Integration Meets Institutional Market Infrastructure
Given this structural transition toward private market-making, the rapid institutionalization of real-world asset (RWA) tokenization fits seamlessly into the new DeFi architecture. Major global exchanges are deploying significant capital to bridge traditional capital markets with blockchain settlement layers. Recent strategic movements include Nasdaq's $100 million strategic investment into Payward (Kraken’s parent company) to advance its tokenized equities strategy, alongside the London Stock Exchange Group’s active deployment of tokenized asset frameworks for its planned 24-hour trading venues scheduled for market rollout.
Institutional assets like tokenized equities, U.S. Treasury bills, and regulated debt instruments cannot survive in public, unhedged AMM pools vulnerable to LVR. The rollout of tokenized stocks across permissionless layer-1 and layer-2 networks relies explicitly on request-for-quote (RFQ) protocols backed by institutional market makers and liquidity providers rather than open community pools. This environment requires deep reference prices from external centralized exchanges, tight spread guarantees, and sophisticated inventory management.
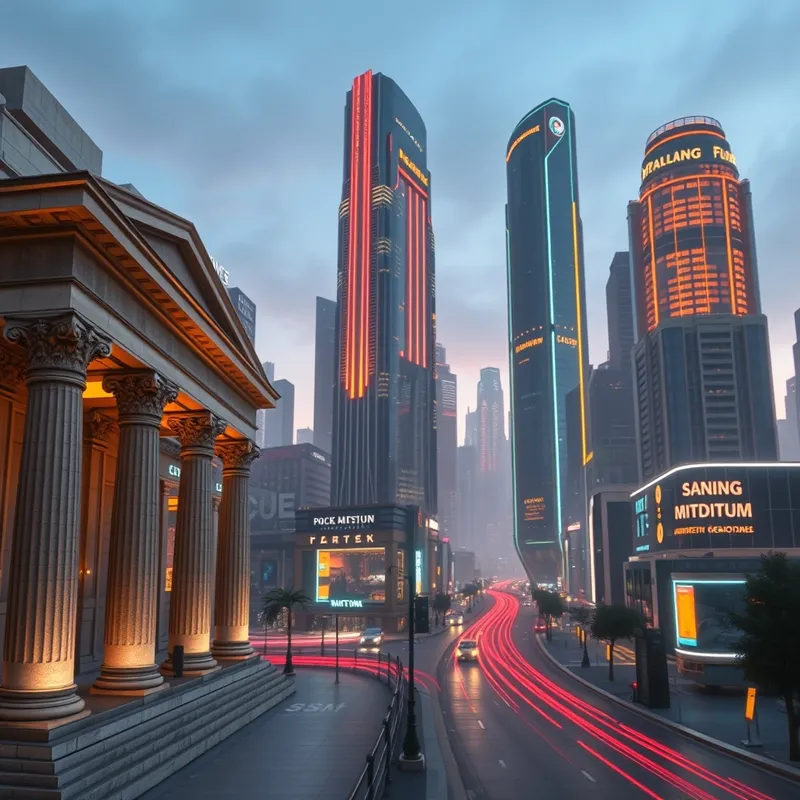
The institutional architecture now emerging across high-speed blockchains completely decouples settlement transparency from execution discovery. While settlement remains verifiable on a public ledger, the execution process—how a price was derived, which market maker received order priority, and how quotes were structured—occurs inside proprietary off-chain algorithms. DeFi has built an efficient, institutional execution environment, but it has done so by adopting the exact structural mechanics of traditional high-frequency finance.
The market structure of decentralized finance is splitting into two isolated operational domains. High-volume, institutional-grade digital assets will trade almost exclusively through permissioned propAMMs and off-chain RFQ networks, while public AMMs will be relegated to long-tail asset discovery and un-priceable speculative tokens. Investors relying on passive LP yields in blue-chip pools face terminal margin compression as professional inventory providers absorb toxic flow and institutional volume.
⚡ PropAMM (Proprietary Automated Market Maker): A closed-source, on-chain market-making system capitalized exclusively by private trading firms using dynamic off-chain pricing algorithms rather than public liquidity pools.
📉 Loss-Versus-Rebalancing (LVR): The quantifiable structural loss sustained by passive liquidity providers when arbitrageurs trade against stale pool quotes using real-time off-chain price data.
📡 RFQ Network (Request-For-Quote): An execution model where decentralized aggregators request private off-chain price quotes from institutional market makers, settling only the winning trade on-chain.
- If propAMM total volume share on major aggregators exceeds 40% → reallocate capital away from passive blue-chip AMM yield pools.
- If DEX aggregator router code transitions to permissioned market-maker inclusion → hedge against governance token value decay in public protocols.
- If block latency on high-throughput chains drops under 200ms → expect institutional RFQ execution capture to reach complete market dominance.
— — coin24.news Editorial
This analysis is synthesized from aggregated market data and institutional research insights. It is provided for informational purposes only and should not be construed as financial advice. Cryptocurrency investments carry high risk; please conduct your own due diligence before making any investment decisions.
Related Intelligence
XRPL credit shift exposes fresh risk: The Underwriting Illusion
TON App Distribution Milestone Hides: Bot metrics mask real demand

XRPL validators weigh unbacked debt: A Credit Fault Line

Circle buys fiat rails to secure USDC: The Last-Mile Illusion

Zoomex Gamifies Retail Copy Trading: The Yield Quicksand
